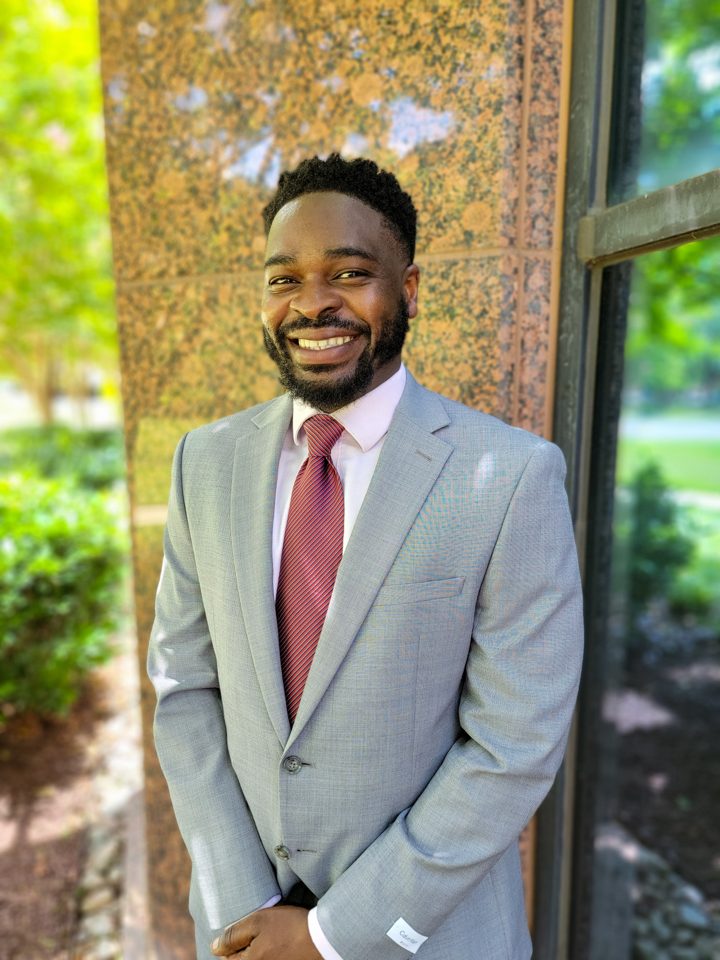
Who you'll actually talk to
Doyin Ogunbajo, CPA
You talk to Doyin Ogunbajo, CPA, the founder, on every engagement. Not a junior analyst reading from a template.
Annual audits and reviews built around how condos actually run: monthly assessments, a reserve fund, a management company handling the cash, and owners who want to know where their money went.
A condo is a small business with 20 to 500 owners as stakeholders. These are the areas we spend the most time on, because they are where associations most often get questions.
We tie billed assessments to the unit ledgers, test collections, and review delinquencies, write-offs and late fees so owner receivables are stated fairly.
Get started →We report reserve balances, contributions and spending, and line them up against your replacement-reserve study so funding levels are clear to the board.
Get started →When a property manager collects and holds association cash, we test deposits, bank reconciliations and disbursement approvals on your behalf.
Get started →Roof, elevator and façade projects often mean a special assessment or a bank loan. We make sure the financials show what was billed, collected and borrowed.
Get started →We review the master policy and deductible exposure, and check that the association’s federal tax filing method matches how its income is reported.
Get started →You get the financial statements, a plain-language summary, and a letter of findings and fixes, written for volunteers who are not accountants.
Get started →The right answer comes from three places: your governing documents, your state, and your lenders. We check all three against your size before recommending one.
The highest level of assurance. We test balances and transactions and give an opinion on the financial statements. Often required by governing documents, a member vote, or a lender.
Limited assurance based on analysis and inquiry rather than detailed testing. A common middle step for smaller associations whose documents allow it.
The statements are assembled from your books with no assurance. Fine for internal use when nothing requires more, but it will not satisfy an audit requirement.
Send us your declaration, bylaws and last year’s financials on a short call. We tell you what they require and what a lender is likely to ask for.
Most audit delays come from missing paperwork, not accounting problems. Pulling these together early shortens the process and the fee.
Year-end statements and reconciliations for every operating and reserve account, plus any CDs or investment accounts.
The unit-by-unit assessment ledger, the delinquency list, and your collection and late-fee policy.
Approved budget, board minutes, the current reserve study, and the master insurance policy and renewals.
The management agreement and the manager’s year-end package, including any change of manager during the year.
Project your reserve fund five years out against major repairs and see if it holds, using your own numbers.
You talk to Doyin Ogunbajo, CPA, the founder, on every engagement. Not a junior analyst reading from a template.
Related: HOA & nonprofit audits · Reserve adequacy tool · Real estate accounting
Book a free 30-minute discovery call to walk through what your declaration requires and where your association’s books stand today.